A growing business needs more than steady sales to move forward. It needs reliable financial records, a clear understanding of cash flow, realistic growth plans, and financial information that lenders can assess with confidence. Without these foundations, even a profitable business can struggle to manage expansion or prepare a finance application.
A Business Accountant Point Cook can help business owners understand their current financial position, identify potential risks, and prepare the information needed to support informed business decisions. Whether you operate a small company, manage a family business, or plan to expand your operations, organised accounting records can make the next stage of growth easier to manage.
For businesses preparing to hire employees, purchase equipment, expand into new markets, or apply for business finance, the right accounting support can help turn financial information into a practical action plan.
This guide explains how a business accountant in Point Cook for growing companies can support financial planning, prepare lender-ready financials, improve cash flow forecasting, and help business owners approach finance applications with greater confidence.
It also covers common preparation mistakes, practical steps you can take before approaching a lender, and the questions worth asking an accountant before making important financial commitments.
What Does a Business Accountant Do for a Growing Business?
A business accountant helps you understand what your financial records reveal about the health and direction of your business. Their role can extend beyond recording transactions and preparing annual accounts to include financial analysis, budgeting, reporting, tax compliance, and growth planning.
For a growing business, this support becomes particularly valuable because financial decisions often involve several moving parts. Increasing sales may require additional stock, more staff, improved systems, or longer payment terms for customers. Each decision affects cash flow differently.
A business owner might see rising revenue and assume the company is ready to expand. However, the accounting records may reveal that customer payments are arriving late, operating expenses are increasing, or too much working capital is tied up in unpaid invoices.
A qualified accountant can help identify these issues before they become serious obstacles.
Why Financial Preparation Matters Before Expansion
Growth usually increases both opportunity and financial responsibility. Businesses may need to fund additional inventory, cover higher operating expenses, invest in technology, or maintain sufficient cash reserves while new revenue develops.
Before committing to expansion, review the following areas:
- Profitability: Is the business consistently generating a sustainable operating profit?
- Cash flow: Can the business meet its obligations when payments fall due?
- Working capital: Are enough funds available to support everyday operations?
- Financial records: Are transactions, liabilities, and business expenses recorded accurately?
- Future commitments: Can the business manage additional repayments, staffing costs, or supplier obligations?
A business accountant helps connect these areas so that growth decisions are based on evidence rather than assumptions.
For example, a Point Cook business may receive several large customer orders but need to pay suppliers and employees before customers settle their invoices. Although the orders may be profitable, the timing difference can create a temporary cash shortage. Recognising this gap early allows the owner to consider payment terms, working capital arrangements, or a more suitable delivery schedule.
How Accounting Services Help Prepare Your Business for Growth
Reliable Accounting Services Point Cook can help business owners move from reactive bookkeeping to structured financial management. Instead of reviewing accounts only at tax time, regular accounting support gives you a clearer picture of business performance throughout the year.
This is particularly important when you are considering expansion or preparing documents for a lender.
1. Reviewing Financial Statements Before Making Decisions
Financial statements provide a structured view of how your business is performing. The three key reports are the profit and loss statement, balance sheet, and cash flow statement.
Each report answers a different question.
- Profit and loss statement: Is the business generating a profit from its operations?
- Balance sheet: What does the business own, and what does it owe?
- Cash flow statement: Where is cash coming from, and where is it going?
A business can report a profit while still experiencing cash flow difficulties. This can happen when customers have not paid their invoices, inventory has increased, or loan repayments and other obligations fall due before cash is received.
Reviewing all three reports together gives business owners a more complete picture.
Practical example: Imagine a local service business that has secured several new contracts. Its profit and loss statement shows stronger revenue, but its balance sheet reveals a growing amount of unpaid customer invoices. By examining these figures, the accountant can help the owner understand whether the business has sufficient working capital to take on additional work.
Before pursuing expansion, ask your accountant to explain any significant changes in revenue, operating expenses, debt, receivables, and available cash.
2. Building a Realistic Growth Plan
A growth plan should explain how the business intends to expand and what financial resources will be required to achieve that objective.
An accountant can help translate your business goals into financial projections. These projections might cover expected sales, staffing requirements, operating expenses, equipment purchases, working capital, and future financial obligations.
For instance, a business planning to hire two additional employees should consider more than their salaries. It should also account for superannuation, leave entitlements, recruitment, training, equipment, and the time required for new employees to contribute to revenue.
A practical growth plan should include:
- Current financial performance and available resources.
- Expected changes in sales and operating expenses.
- Additional staffing, equipment, or inventory requirements.
- Potential risks that could affect revenue or cash flow.
- A realistic timeline for implementing the expansion.
- Financial measures to monitor progress.
This approach helps owners decide whether to proceed immediately, expand in stages, or strengthen their financial position first.
3. Improving Financial Decisions With Monthly Reporting
Annual financial statements are useful, but they may not provide enough detail for businesses experiencing rapid change.
Monthly reporting gives owners more frequent insight into performance. Depending on the business, a useful monthly reporting pack may include:
- Actual revenue compared with budget.
- Operating expenses and profit margins.
- Outstanding customer invoices.
- Supplier bills and upcoming obligations.
- Cash balances and short-term cash requirements.
- Changes in loans, liabilities, and working capital.
The purpose is not simply to produce more reports. It is to identify meaningful changes early enough to respond.
For example, if sales remain stable but operating expenses rise for three consecutive months, the owner can investigate whether the increase relates to staffing, supplier costs, subscriptions, or inefficient processes.
Regular reviews also help identify whether a growth strategy is producing the expected results.
Practical tip: Schedule a monthly financial review and agree on a small set of performance indicators that matter to your business. Depending on your industry, these may include gross profit margin, debtor days, cash reserves, operating profit, and recurring revenue.
How to Prepare Lender-Ready Financials for a Business Finance Application
Lenders generally need to understand whether a business can meet its proposed financial commitments. The documents they request vary by lender, loan type, business structure, and application circumstances.
Preparing lender-ready financials means ensuring your records are accurate, consistent, current, and supported by appropriate evidence.
A Business Accountant can help organise the financial information, identify inconsistencies, and explain the figures a lender may need to assess.
1. Organise Your Financial Documents
Start by identifying which documents are required for your particular application. Depending on the lender and circumstances, these may include:
- Recent profit and loss statements.
- Current balance sheets.
- Business tax returns and relevant notices of assessment.
- Business activity statements (BAS).
- Business bank statements.
- Accounts receivable and accounts payable reports.
- Existing loan statements and repayment schedules.
- Cash flow forecasts and business plans.
- Evidence supporting the proposed use of finance.
Some lenders may also request personal financial information, particularly for small businesses, sole traders, partnerships, or applications involving personal guarantees.
Do not assume that every lender uses the same checklist. Confirm the requirements directly and provide the records for the requested period.
An accountant can help reconcile the information across your accounting software, tax records, and bank statements so the figures are consistent.
2. Reconcile Bank Accounts and Outstanding Transactions
Bank reconciliation is a fundamental step in preparing financial information.
It involves comparing recorded transactions with bank statements and investigating differences. These may include missing transactions, duplicated entries, incorrectly classified expenses, or payments that have not been allocated to the right accounts.
Before a finance application, check that:
- All relevant bank accounts are reconciled.
- Business income and expenses are recorded correctly.
- Customer receipts are allocated to the appropriate invoices.
- Supplier payments are recorded against the correct bills.
- Loan balances and repayments are up to date.
- Significant transactions have supporting documentation.
These checks can reduce the likelihood of avoidable questions during the application process.
If an accountant identifies an error, the correction should be supported by the underlying records. Financial statements should never be adjusted simply to make the business appear more attractive to a lender.
3. Explain Changes in Financial Performance
A lender may want to understand why revenue, profit, expenses, or liabilities have changed.
A clear explanation supported by evidence can help provide context.
For example, revenue may have declined because the business temporarily lost a major contract. Alternatively, expenses may have increased because the company invested in new equipment that is expected to support future operations.
The explanation should distinguish between temporary changes and ongoing financial pressures. It should also avoid presenting uncertain future revenue as guaranteed income.
Your accountant can help prepare a straightforward explanation of significant movements and identify the supporting documents that may be useful.
4. Understand What Lenders Assess
Although assessment criteria differ, lenders commonly consider several aspects of a business’s financial position.
| Assessment area | What it helps demonstrate |
|---|---|
| Profitability | Whether the business generates sustainable earnings |
| Cash flow | Whether funds are available to meet obligations |
| Existing liabilities | How current financial commitments affect capacity |
| Trading history | How the business has performed over time |
| Financial records | Whether the information is consistent and supportable |
| Purpose of finance | How the requested funds will be used |
| Forecast assumptions | Whether expected future performance is realistic |
An accountant can help you prepare and interpret this information. However, the lender retains responsibility for its credit assessment, and professionally prepared financial statements do not guarantee approval.
Why Cash Flow Forecasting Is Essential for Business Growth
Cash flow forecasting estimates when money is expected to enter and leave the business. It helps owners anticipate funding gaps before they occur.
For businesses planning to expand, this is particularly important because additional sales do not always produce immediate cash receipts.
A company may need to purchase materials, pay employees, and cover operating expenses before customers settle their invoices. Without a forecast, the owner may discover the shortfall only when an important payment becomes due.
How an Accountant Builds a Useful Cash Flow Forecast
A practical forecast begins with the current cash position and maps expected receipts and payments across an appropriate period.
Depending on the business, the forecast may include:
- Expected customer receipts based on realistic payment dates.
- Supplier payments and recurring operating expenses.
- Payroll, superannuation, and tax obligations.
- Equipment purchases and planned capital expenditure.
- Existing debt repayments.
- Proposed finance repayments, where relevant.
- Seasonal changes in demand or payment patterns.
For an expanding business, a rolling 13-week cash flow forecast can be a useful short-term planning tool. Longer-term forecasts can help assess the financial implications of major growth decisions.
The forecast should be updated as actual results become available.
Use Different Scenarios Instead of One Optimistic Forecast
One of the most useful forecasting practices is to prepare alternative scenarios.
Base case: Sales and expenses follow the most reasonable current expectations.
Downside case: Customer payments are delayed, sales are weaker, or expenses are higher than expected.
Growth case: New contracts, additional staff, or expansion plans increase both revenue and operating requirements.
Comparing these scenarios helps owners understand how sensitive their plans are to changing conditions.
For example, a business may expect a new contract to increase monthly revenue. However, if the customer pays after 45 days while suppliers require payment within 14 days, the contract could increase short-term funding pressure.
A forecast can reveal this mismatch and help the business consider practical responses before committing to the contract.
Expert tip: Base projections on documented assumptions, such as existing customer payment patterns, signed contracts, supplier terms, and known operating commitments. Clearly label estimates and distinguish them from confirmed income.
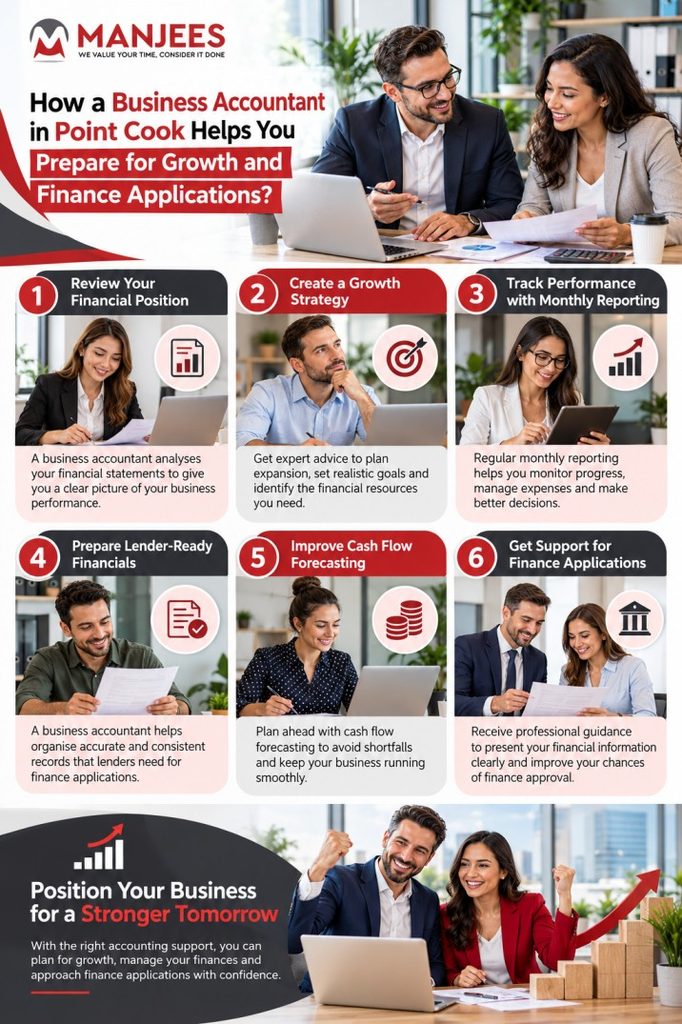
How a Business Accountant Point Cook Supports Finance Applications
Preparing for finance is not only about collecting documents. It is also about understanding whether the proposed borrowing fits the business’s financial position and plans.
A business accountant in Point Cook for growing companies can help owners assess the financial implications of borrowing before submitting an application.
Assess Whether the Proposed Finance Fits Your Business
Before applying, clarify the purpose of the funds. The requirements for purchasing equipment may differ from those for funding inventory, refinancing existing debt, or supporting a business expansion.
Your accountant can help assess:
- How the proposed finance supports the business plan.
- Whether projected cash flow can accommodate repayments.
- How existing liabilities affect the overall position.
- Whether the business has sufficient working capital.
- What could happen if sales fall below expectations.
- Whether the proposed timing of the investment is financially appropriate.
This analysis helps you understand the risks as well as the potential benefits of borrowing.
Match Financial Evidence to the Purpose of the Application
The documents you provide should help explain why the finance is needed and how it will be used.
For example, a business applying for equipment finance may need to provide equipment details, supplier documentation, and forecasts showing how the investment supports operations. A business seeking working capital may need to explain its trading cycle, customer payment terms, and short-term cash requirements.
The supporting information should be consistent with the financial statements and the assumptions used in the forecast.
An accountant can help identify gaps before submission and prepare a clear financial summary where appropriate. This can make it easier to answer follow-up questions without scrambling to locate missing records.
Keep Tax Compliance and Business Records Up to Date
Outstanding tax lodgements, unreconciled transactions, and inconsistent records can complicate a finance application.
Australian businesses should pay attention to their relevant tax and reporting obligations, including BAS lodgements, GST records where applicable, PAYG withholding, superannuation obligations, and income tax reporting.
The exact requirements depend on the business structure and circumstances.
A qualified accountant can help identify overdue obligations, organise supporting records, and clarify what needs to be addressed before an application proceeds. If an obligation cannot be met on time, discuss the situation with your accountant rather than ignoring it.
Common Mistakes Businesses Make Before Applying for Finance
Even a business with good growth prospects can make its application more difficult by overlooking basic financial preparation.
1. Relying on Revenue Instead of Cash Flow
Strong sales do not necessarily mean sufficient cash is available.
A business may have significant outstanding invoices but still need to pay wages, suppliers, and tax obligations. Review the timing of cash receipts and payments rather than relying on revenue figures alone.
2. Leaving Bookkeeping Until the End of the Financial Year
When transactions are recorded irregularly, errors and missing documents can accumulate.
Maintaining records throughout the year makes it easier to produce current reports, explain unusual transactions, and respond to information requests.
3. Using Unrealistic Growth Projections
Forecasts based on hoped-for sales rather than reasonable evidence can create an inaccurate picture of future performance.
Base assumptions on existing trading results, confirmed contracts, reliable customer information, and realistic operating capacity. Where uncertainty exists, show alternative scenarios.
4. Mixing Personal and Business Transactions
Mixing personal and business spending can make financial records harder to interpret. It can also complicate the assessment of business expenses, drawings, and cash flow.
Maintain appropriate separate accounts and document transactions accurately. If personal transactions have already been recorded in business accounts, ask your accountant to help classify and reconcile them correctly.
5. Assuming Finance Approval Is Guaranteed
An accountant can help improve the quality of an application, but cannot guarantee a lender’s decision.
Approval may depend on credit history, security, industry risk, existing commitments, lender policies, and other factors outside the accountant’s control.
A realistic preparation process focuses on accurate records, a credible business case, and an honest assessment of repayment capacity.
Manjees Accounting and Taxation Services offers reliable business accounting, tax advice, bookkeeping, and financial support to help businesses in Point Cook manage their finances confidently.
Practical Growth Strategies to Discuss With Your Accountant
The best time to review your financial position is before a major decision becomes urgent.
Establish a Regular Financial Review
Set aside time each month to review performance, cash flow, unpaid invoices, upcoming liabilities, and progress against your budget.
Use the meeting to answer specific questions:
- Are sales and margins developing as expected?
- Which customers have overdue invoices?
- Are operating expenses increasing faster than revenue?
- What financial obligations are due in the coming weeks?
- Is the business prepared for its next planned investment?
Regular reviews help turn accounting information into actionable decisions.
Improve Debtor Management
Late customer payments can restrict growth even when a business has a healthy order book.
Review payment terms, follow up on overdue invoices, and identify customers who repeatedly pay late. Where commercially appropriate, consider deposits, staged billing, or milestone payments for larger projects.
An accountant can help assess how debtor days affect working capital and whether changes to credit terms could improve cash flow.
Plan for Tax and Other Obligations
Tax and statutory obligations should be incorporated into cash flow forecasts rather than treated as unexpected expenses.
Set aside appropriate funds based on the business’s circumstances, review upcoming lodgement dates, and keep supporting documentation organised. The amount and timing of obligations will depend on the entity, activity, and applicable requirements.
This planning helps reduce the risk of using funds needed for tax or other liabilities to finance day-to-day growth.
Review the Business Structure and Financial Controls
As a business expands, its original administrative processes may no longer be sufficient.
Consider whether the current business structure, accounting software, approval procedures, and reporting processes remain suitable. Changes in staffing, ownership, business activities, or financing arrangements may justify a professional review.
Structural and tax decisions should be made with appropriate advice, taking the business’s specific circumstances into account.
Choosing the Right Business Accountant in Point Cook
Not every business needs the same level of accounting support. A sole trader with straightforward transactions may have different requirements from a company managing employees, multiple revenue streams, and a finance application.
When evaluating an accountant, consider the following questions:
- Do they understand your business structure and industry?
- Can they explain financial statements in practical, understandable terms?
- Do they provide regular reporting and cash flow forecasting?
- Can they assist with financial documentation for finance applications?
- Are they clear about their scope of work and professional responsibilities?
- Do they communicate potential risks and limitations honestly?
- Are they appropriately qualified and experienced for the services you require?
Ask how the accountant would approach your specific growth plans. Their response should demonstrate an understanding of the financial challenges involved, rather than relying on broad promises.
Accounting Services Point Cook should be assessed according to the actual support your business needs, whether that involves bookkeeping oversight, financial statements, tax compliance, budgeting, or growth planning.
For additional local context, you can also explore the relevant Point Cook business information when researching your options.
Conclusion
Preparing for business growth and finance applications requires more than having a profitable month or collecting documents at the last minute. It involves understanding financial performance, maintaining reliable records, forecasting cash requirements, and assessing the risks associated with future commitments.
A Business Accountant in Point Cook can help business owners bring these elements together through accurate financial statements, regular monthly reporting, practical cash flow forecasting, and organised finance documentation.
For growing businesses, the goal is to make decisions based on reliable information rather than assumptions. Whether you are planning to hire staff, invest in equipment, expand operations, or approach a lender, early preparation can help you understand your options and identify potential challenges.
If your business is preparing for its next stage, review your current financial records and identify the gaps that need attention. Contact an appropriate accounting professional by phone or through an enquiry form to discuss your growth plans, reporting requirements, and finance preparation needs.
A clear financial picture will not guarantee finance approval or business success, but it can help you approach both with greater confidence and a more informed plan.
Frequently Asked Questions
What financial reports should I prepare before applying for business finance?
Start by checking the lender’s document requirements. Commonly requested reports include a recent profit and loss statement, balance sheet, cash flow information, business tax returns, BAS records, and business bank statements.
You may also need an accounts receivable report, details of existing liabilities, and a forecast explaining how the proposed finance will be used and repaid.
The reporting period and additional documents depend on the lender, finance product, business structure, and application. Ensure that figures are current and consistent across the records you provide.
Why is cash flow forecasting important when planning business growth?
Cash flow forecasting helps estimate when money will enter and leave the business. It can reveal periods when supplier payments, wages, tax obligations, and loan repayments may exceed available funds.
This is especially important when sales increase but customer payments arrive later. A forecast allows you to identify potential funding gaps, consider alternative scenarios, and make more informed decisions before committing to additional expenses.
When should I contact an accountant before applying for finance?
Contact an accountant during the planning stage, ideally before submitting an application or committing to a major investment.
Early preparation gives you time to reconcile records, address reporting gaps, review existing obligations, and assess whether the proposed repayments are realistic.
If the business has overdue lodgements, inconsistent records, or significant changes in profitability, allow additional time to investigate and resolve those issues.
Where should a business owner start when preparing lender-ready financials?
Begin with the lender’s checklist and your most recent accounting records. Reconcile bank accounts, check outstanding invoices and bills, confirm loan balances, and ensure that the financial statements reflect the underlying transactions.
Next, prepare a realistic cash flow forecast and gather documents supporting the purpose of the finance. Keep copies of important contracts, invoices, and other relevant evidence so that figures can be explained when questions arise.
Who can help a Point Cook business assess its financial readiness for expansion?
A suitably qualified accountant can help assess profitability, working capital, liabilities, cash flow, and the financial implications of a growth plan.
Depending on the decision, you may also need advice from a lender, finance broker, lawyer, or other specialist. The accountant’s role is to help you understand your financial position and prepare reliable supporting information, while the lender determines whether the application meets its lending criteria.
How can I tell whether my business is financially ready to grow?
Look beyond increasing sales. Review profitability, cash flow, outstanding debts, working capital, operating capacity, and the financial commitments that expansion would introduce.
Prepare a forecast that includes both expected results and a downside scenario. If the business can manage its obligations under reasonable assumptions and has a credible plan for funding additional activity, it may be better positioned to proceed.
Financial readiness is not a guarantee of success, but a structured assessment can help identify weaknesses before they become more difficult to address.